The short answer is: it depends. Jewellery insurance is worth it for many people, but not everyone. The decision comes down to the value of your pieces (both monetary and sentimental), how you use them, what you could afford to replace out of pocket, and the type of cover you choose.
Here’s how to work through it.
1. What is the jewellery actually worth?
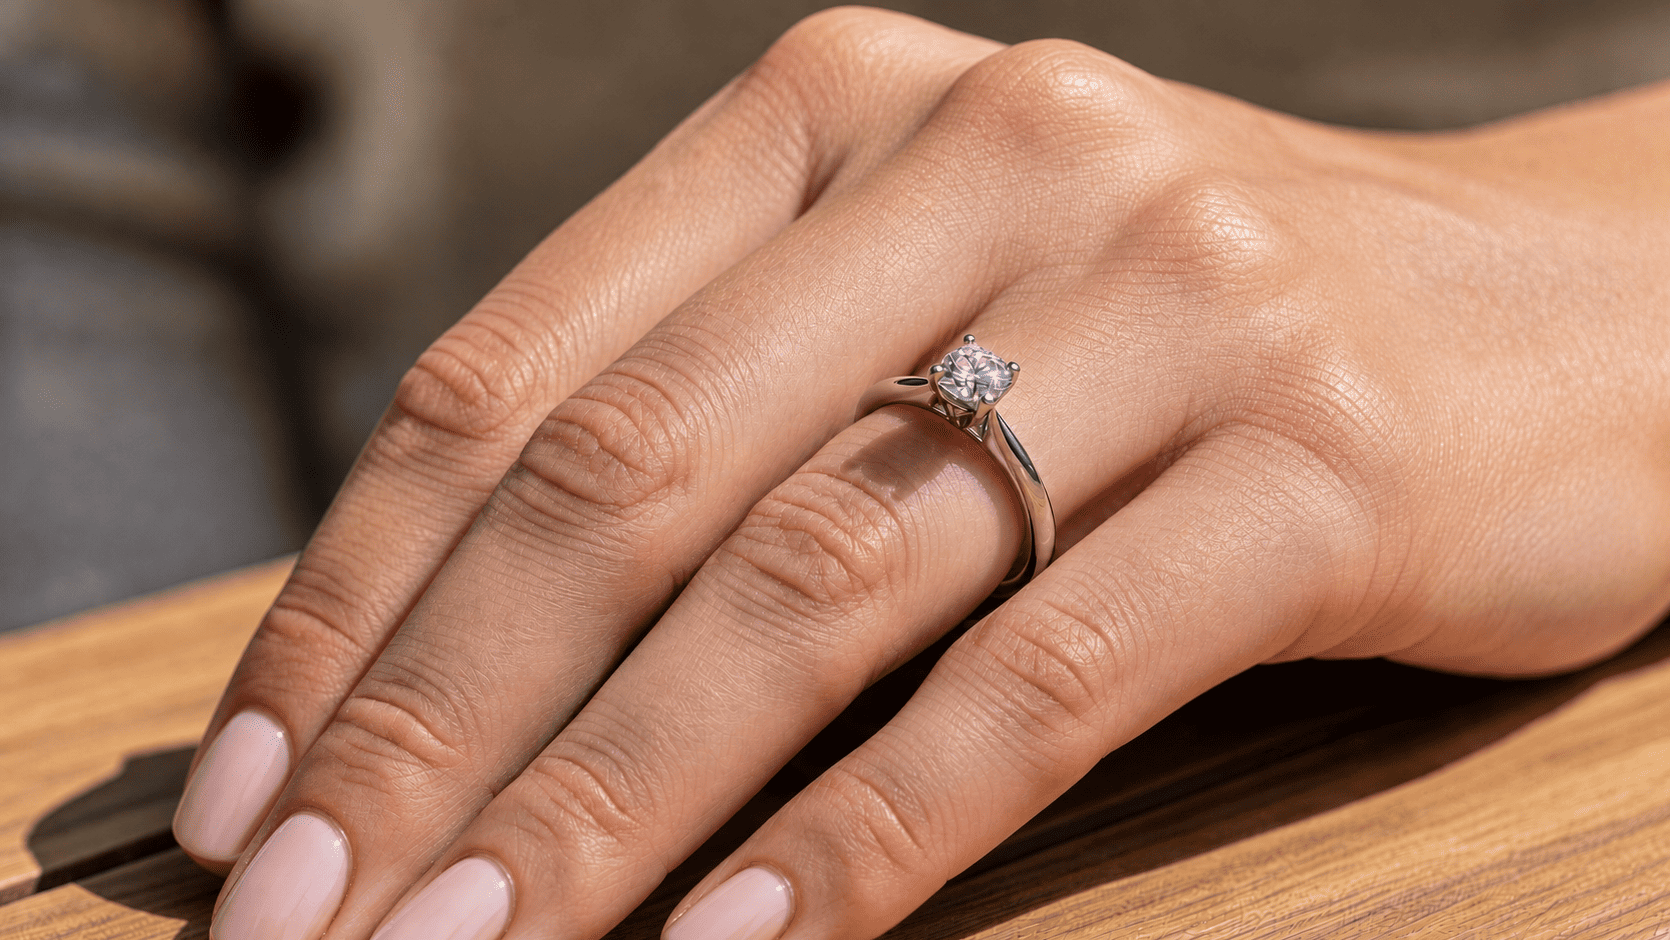
If a piece is worth several thousand dollars or more, insurance is more likely to make sense. Losing or damaging a $10,000 engagement ring or a high-value necklace can create a significant financial hit.
Sentimental value also matters. Heirlooms, engagement rings, or custom pieces tied to important moments are often difficult or impossible to replace exactly. Insurance won’t restore the original item, but it can cover the cost of a high-quality replacement or replica.
For lower-value items that sit in a safe most of the time, the case for specialist insurance is weaker.
2. How exposed is the jewellery?
Risk depends on how and where you wear or store the pieces.
Higher risk factors include:
- Wearing the jewellery regularly
- Travelling with it (including interstate or overseas)
- Living in an area with higher burglary or disaster risk
- Situations where rings can slip off (beaches, pools, cold water, sunscreen)
Lower risk situations include jewellery that stays in a secure safe and is rarely worn. In those cases, some people choose to self-insure.
Specialist jewellery policies often cover accidental loss and “mysterious disappearance” (for example, a ring slipping off unnoticed), which many home and contents policies limit or exclude, especially away from home.
3. Could you afford to replace it yourself?
Ask whether replacing the item would meaningfully strain your finances. A $10,000 loss might be manageable for some households and disruptive for others.
Insurance spreads that risk into an annual premium. If you have strong emergency savings and view the jewellery as a non-essential luxury, self-insuring can be reasonable. If a loss would force you to use high-interest credit or delay other goals, cover becomes more attractive.
4. What does the policy actually cover?
Not all jewellery cover is the same. Check:
- Accidental loss, theft and damage (not just theft)
- Cover away from home and overseas
- Excess (some specialist policies offer $0 excess)
- How claims are settled (cash, or replacement through a preferred jeweller)
- Whether the value is fixed or needs regular updating
Home and contents policies sometimes cover jewellery, but often with item limits, restricted away-from-home cover, and replacement through the insurer’s own network. Specialist jewellery insurance is usually designed to address these gaps.
Centrestone policies, for example, include worldwide cover for accidental loss, theft and damage, $0 excess as standard, free annual value updates, and the ability to return to your chosen jeweller for replacement.
5. Does the cost make sense?
Jewellery insurance typically costs a small percentage of the item’s insured value each year. For many people the annual premium is far lower than the cost of replacing a higher-value piece.
You will also need a valuation or receipt. Once you have that, getting a quote is straightforward and shows the actual cost for your situation.
Weigh the premium against the financial and emotional impact of a loss. For high-value or frequently worn pieces, many people decide the ongoing cost is worth the peace of mind. For lower-value items kept securely at home, it may not be.
When jewellery insurance is usually worth it
- The piece has significant monetary or sentimental value
- You wear or travel with it
- Replacing it out of pocket would be painful
- You want cover for accidental loss and worldwide protection that home and contents policies often limit
When it may not be necessary
- The jewellery is low value and rarely worn
- It is kept securely at home
- You can comfortably replace it yourself
Next step
The clearest way to decide is to get a quote based on your actual pieces and compare it with what you could afford to lose. It takes a few minutes and shows whether the cost is reasonable for your situation.
Get an instant quote from Centrestone Jewellery Insurance.
Centrestone Jewellery Insurance is underwritten by Berkley Insurance Australia (ABN 53 126 559 706, AFSL 463 129). This article contains general information only and does not take into account your objectives, financial situation or needs. Consider the Product Disclosure Statement (PDS) and Target Market Determination (TMD) before deciding whether this product is right for you.
It’s advisable to consult with an insurance specialist or financial advisor to discuss your specific needs and circumstances before deciding whether jewellery insurance is the right choice for you.
For more information on jewellery insurance read the following article:
Insuring your jewellery